
Parametric Earthquake Insurance Explained: How Catastrophe Bonds Work
Parametric earthquake insurance pays out against a measured trigger rather than an assessed loss, which buys speed at the cost of basis risk. This explainer covers trigger design for earthquakes, how catastrophe bonds are actually issued through a bankruptcy-remote special purpose vehicle with collateral held for investors, and the institutional steps a sovereign needs before signing. It closes with why Nepal's current seismic network density makes a credible trigger harder than it sounds.
Parametric Earthquake Insurance Explained: How Catastrophe Bonds Work
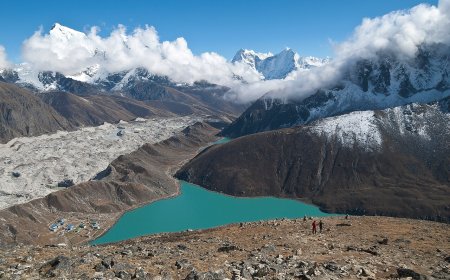
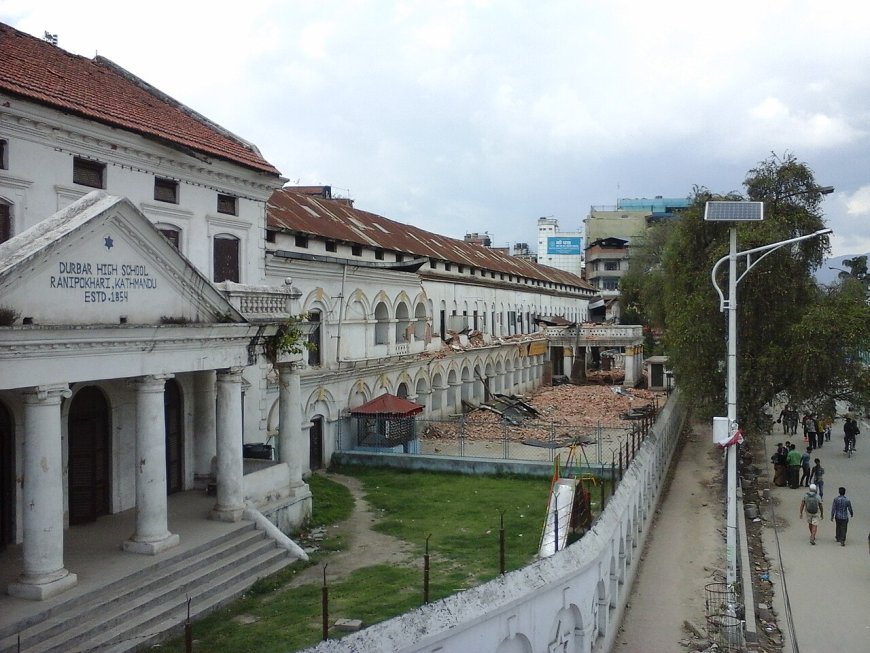
Nepal sits on a seismically active belt where large quakes can strike with little warning. The 2015 Gorkha earthquake, magnitude 7.8, killed nearly 9,000 people and left a reconstruction bill running into the billions. In that kind of event the bottleneck is rarely generosity; it is speed. Money committed weeks after the shaking arrives long after the emergency phase has passed.
Parametric earthquake insurance is one answer to that timing problem. Instead of paying against an assessed loss, it pays against a measurement. Below is how the mechanism works, where it misfires, how catastrophe bonds fit into it, and what Nepal would actually need in place before a deal like this could be signed.
Parametric earthquake insurance: the trigger, and the basis risk that comes with it
A parametric earthquake insurance policy pays when a pre-agreed measurement crosses a pre-agreed threshold. Nothing is adjusted after the fact, no loss assessor visits the site, and the payout comes out of a formula rather than a claim file. That measurement is called the trigger, or the index.
Earthquake triggers are usually built on one of three things: moment magnitude, peak ground acceleration (PGA), or shaking intensity on a scale such as MMI (Modified Mercalli Intensity). Depth is not a payout index. It feeds the hazard model that tells you which thresholds are sensible, but nobody settles a bond on depth alone, because depth on its own says little about how hard the ground moved at a given place.
The data source matters as much as the parameter. A trigger needs a network of certified stations, an agreed rule for which stations count, and a protocol for what happens if a station goes offline during the event. Get that wrong and the contract becomes an argument waiting to happen.
Basis risk, in one example
Set the trigger at magnitude 7.5 recorded at a named station. An event reads 7.6 and the contract pays, but the shaking damages about $2 million worth of property. The payout overshoots the loss. Another event reads 7.4 and the contract does not pay, while the shaking destroys $20 million worth of infrastructure. The payout undershoots by the whole amount. That gap between what the index says and what happened on the ground is basis risk, and it is the price of speed.
The shift in who argues with whom is the other half of the trade. A traditional indemnity policy puts the insurer and the insured into a negotiation over the loss amount, with adjusters, photographs and paperwork. A parametric contract moves the argument upstream: was the index reading correct, and did the chosen index represent the risk honestly in the first place?
How a catastrophe bond actually works
A catastrophe bond is how a government, reinsurer or large company hands seismic risk to capital markets investors. The sponsor does not issue the bond itself. It sets up a bankruptcy-remote special purpose vehicle (SPV), and the SPV issues notes to investors. Investor money goes into a collateral account, typically invested in low-risk securities, and the SPV pays the coupon out of that collateral plus the premium the sponsor pays in.
If the trigger fires, the SPV releases the agreed portion of the collateral to the sponsor, and investors lose that much principal. If nothing fires by maturity, investors get their principal back. The sponsor's exposure is capped at the premium it paid, and the SPV is structured so that a sponsor insolvency cannot drag the collateral down with it. That isolation is the point of the whole arrangement. Investors are taking earthquake risk, not credit risk.
One correction to the usual pitch: settlement is not instant. Verifying the index reading, confirming it against the contract's rules and moving collateral typically takes weeks, not days. Some risk pools move faster by design, but 'the money lands tomorrow' is not how these deals are documented.
What a sovereign deal looks like on the ground
At national scale the sponsor is the government, or an agency acting for it. The trigger still works the same way. What changes is the amount of institutional plumbing required before anyone signs. A country usually has to secure legal authority to buy cover, get fiscal approval for the premium, build or contract a seismic network reliable enough to serve as an index, appoint a structuring bank, then market the notes to investors who understand what they are buying. None of that fits inside one budget cycle.
Real examples worth reading
The World Bank has sponsored sovereign catastrophe bonds through its IBRD Capital-at-Risk notes. A 2018 transaction transferred $1.36 billion of Chilean earthquake risk, and a 2019 deal covered $225 million of Philippine earthquake and tropical cyclone risk. Both have published term sheets, which makes them useful to read rather than abstract to admire.
The Caribbean Catastrophe Risk Insurance Facility (CCRIF SPC), set up in 2007 as the first multi-country risk pool, is the other well-documented reference point. It sells parametric earthquake and hurricane cover to member governments and has a stated aim of paying claims within 14 days of an event. That narrower window is worth noting, because it shows the settlement timeline is a design choice rather than a law of nature. A pool with pre-committed members and simple indices can move quickly; a capital-markets bond wrapped in an SPV has more moving parts.
Why Nepal is not a plug-and-play case
Nepal has the hazard. Whether parametric earthquake insurance is worth the plumbing depends on whether the country can measure that hazard well enough to write a credible trigger, and right now the honest answer is no, not without more investment in the network.
The national seismic network, run by the National Earthquake Monitoring and Research Centre under the Department of Mines and Geology, has been expanded since 2015. Station spacing across the hills and mountains is still far coarser than a PGA-based trigger would want. A magnitude trigger is less demanding on station count, but it is a blunter instrument, and blunter means more basis risk.
The Kathmandu Valley adds a complication any index designer has to confront. Soft basin sediments amplify shaking in ways that vary street by street, so a station on one side of the valley can read differently from one a few kilometres away. A trigger built on a single station in that setting would be fragile. A grid of stations with a defined averaging rule is more defensible, and costs more to build and keep running.
None of this is a reason to abandon the idea. It is the actual work: pick a parameter, fund the network that measures it, and accept a known mismatch between index and loss in exchange for money that arrives without a damage survey.
Parametric structures do not make earthquakes smaller or rarer. They reorder what happens after one: measurement first, payment second, assessment somewhere far behind. For a country still rebuilding from the last big quake while waiting on the next one, that reordering is the entire proposition.
What's Your Reaction?